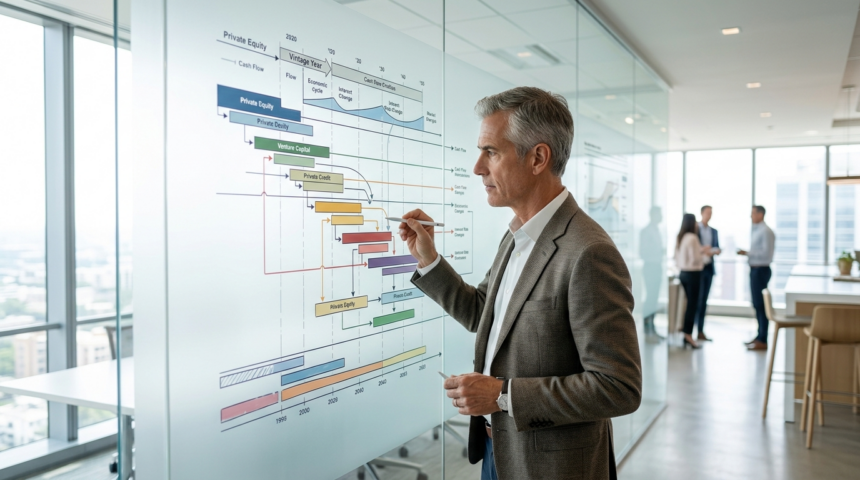
Building a private markets portfolio should start with its overall design, not a search for individual funds, according to a private wealth veteran at EQT. The view shifts attention from product selection to how investments work together across time, risk levels, and market conditions.
The distinction matters as private equity, private credit, infrastructure, and real estate gain attention among wealthy investors. These assets can offer access to companies and projects unavailable through public markets. They can also bring long holding periods, limited liquidity, and complex fee structures.
Construction Comes Before Selection
The EQT veteran described private markets portfolio building as “a construction decision, not a product decision.” That approach calls for investors and advisers to define the portfolio’s purpose before comparing managers or strategies.
A construction-led process may begin with an investor’s return goals, cash needs, time horizon, and tolerance for losses. It can then set allocations across different private market strategies and investment years.
Only after that work would specific funds or managers enter the discussion. This sequence may help investors avoid building a collection of attractive products that fail to function as one portfolio.
Timing Creates a Distinct Challenge
Private investments differ from listed stocks and bonds because capital is often committed before it is invested. Fund managers may call that capital over several years. They may return proceeds on an uncertain schedule.
This structure makes cash planning central to portfolio design. Investors must maintain enough liquid assets to meet capital calls, including during periods of public market stress.
Commitments made across several years can also reduce reliance on a single market entry point. A steady commitment plan may spread exposure across economic cycles and pricing conditions. However, it does not remove the risk of loss.
- Liquidity needs should be assessed before commitments are made.
- Allocations should reflect strategy, geography, and investment year.
- Fees, performance measures, and reporting practices require close review.
- Manager selection should support the portfolio plan, rather than define it.
Access Does Not Replace Due Diligence
Private market products can vary widely in structure and quality. Two funds carrying the same strategy label may use different levels of debt, target different businesses, or follow different exit plans.
That variation places greater weight on manager research. Investors may need to study team stability, prior results, valuation methods, conflicts of interest, and the source of past returns.
The construction approach does not dismiss product selection. Instead, it places that decision within a wider plan. A highly rated fund may still be unsuitable if it adds too much exposure to one sector or creates an unmanageable commitment schedule.
Advisers Face a Broader Planning Role
For wealth advisers, the argument points to a move from product distribution to long-term portfolio oversight. Advisers must connect private investments with a client’s public holdings, spending plans, tax position, and estate needs.
There are also limits to the approach. Private assets may be difficult to value, and performance reports often arrive later than public market data. Investors can face years without an easy route to sell. Diversification may reduce concentration, but it cannot guarantee returns or liquidity.
EQT’s framing offers a practical test for investors considering private markets: decide what role the assets should play before choosing how to gain exposure. The next issues to watch are commitment pacing, liquidity management, and whether advisers can provide clear reporting across multiple funds. In that setting, portfolio discipline may matter as much as access to sought-after managers.