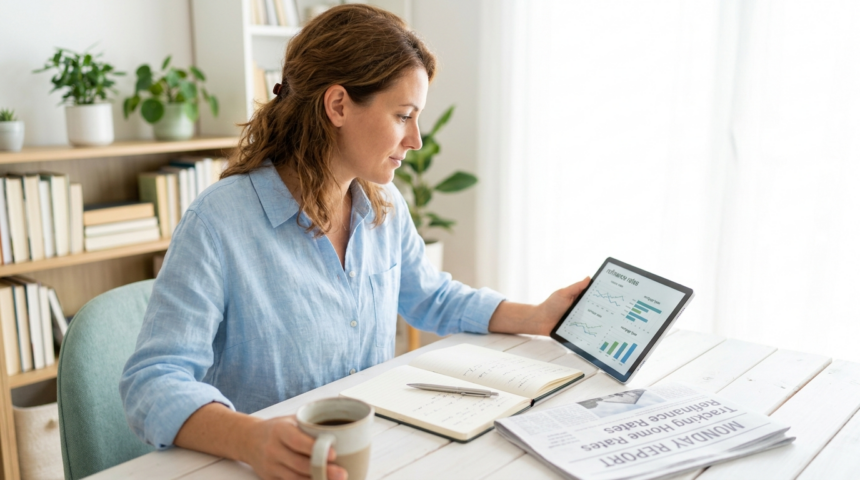
A Monday report directs homeowners to compare average refinancing rates across several mortgage types before replacing an existing home loan. The brief notice does not identify a publication date, market, lender sample, or specific rate figures.
The central message is simple: borrowers should review more than one loan category. Rates can differ by mortgage structure, repayment period, borrower profile, and lender. Those differences may change the cost of refinancing.
“See Monday’s report on average refi rates on different types of home loans.”
Why Loan Type Matters
Refinancing replaces a current mortgage with a new one. Homeowners often refinance to seek a lower rate, change the loan term, or move between adjustable and fixed payments.
Average rates offer a useful market reference, but they are not guaranteed offers. A borrower’s quoted rate may depend on credit history, home equity, income, debt, property type, and discount points.
Common refinancing choices may include:
- Fixed-rate loans with repayment periods such as 15 or 30 years
- Adjustable-rate mortgages with rates that may change later
- Government-backed loans for eligible borrowers
- Cash-out refinancing, which converts part of home equity into borrowed funds
Each option carries a different balance of payment size, interest expense, and risk. A shorter fixed term may reduce total interest but increase the monthly payment. An adjustable loan may start lower, yet future changes can make budgeting harder.
Missing Data Limits Direct Comparisons
The notice does not provide the averages contained in Monday’s report. It also omits the period used to calculate them and whether the figures include fees or points.
Those details matter because mortgage rates can move from day to day. A national average may also differ from offers available in a specific state or metropolitan area.
Borrowers should confirm whether published figures represent purchase mortgages or refinance loans. Refinance pricing can differ from purchase pricing, even for similar borrowers and properties.
Costs Can Offset a Lower Rate
A lower advertised rate does not always produce immediate savings. Refinancing may involve appraisal charges, title services, lender fees, taxes, insurance costs, and prepaid interest.
The break-even period is a key measure. It estimates how long monthly savings must continue before they recover upfront expenses. Homeowners who expect to sell or repay the loan soon may not reach that point.
Extending the repayment term can also lower a monthly bill while increasing interest paid over time. Borrowers should compare total projected costs, not just the first payment.
What Borrowers Should Review
Consumers evaluating Monday’s averages can request written estimates from several lenders using the same loan amount and term. Consistent comparisons help separate rate differences from changes in fees or loan design.
They should also examine the annual percentage rate, closing costs, monthly principal and interest, cash required at closing, and any prepayment conditions. Independent housing or financial counselors may help borrowers assess complicated offers.
The Monday report may provide a timely snapshot, but its value depends on the data and methods behind it. Homeowners should watch subsequent rate movements, compare matching products, and calculate long-term costs before refinancing.