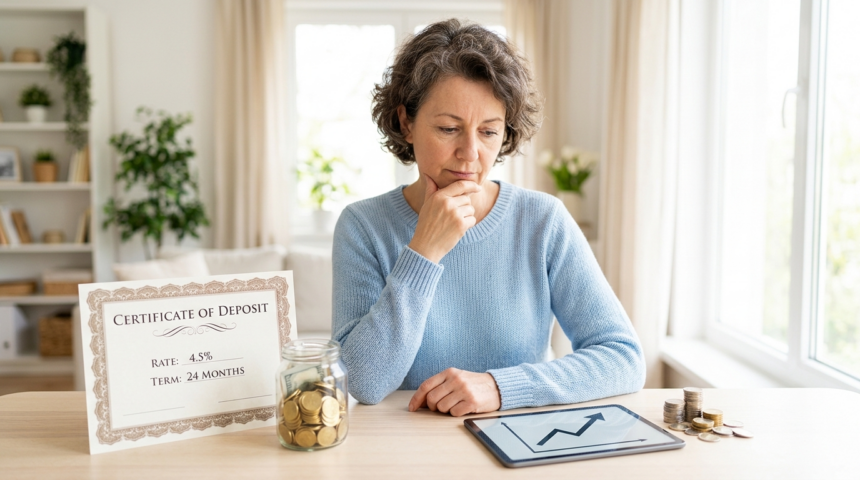
The next move in interest rates could reshape returns on certificates of deposit, forcing savers to weigh guaranteed income against the risk of locking money away too soon.
The central question for depositors is simple: “What’s next for rates and what does that mean for certificates of deposit?” The answer depends on inflation, economic growth, employment, and decisions by central banks. It also depends on how quickly banks adjust the rates offered to customers.
Why Rate Direction Matters
Certificates of deposit, commonly called CDs, pay a fixed rate for a set period. Terms can range from a few months to several years. In return, customers generally agree not to withdraw their money before maturity.
CD yields often move in the same broad direction as central bank policy rates. However, banks do not follow every policy change at the same speed. Each institution also considers its funding needs, competition, and expectations for future rates.
If policymakers are expected to cut rates, banks may lower CD offers before an official decision. Longer-term rates can fall first because they reflect forecasts for several years.
If rates remain high, short-term CDs may continue offering competitive returns. Another rate increase could improve new offers, although existing fixed-rate CDs would not receive the higher yield.
The Choice Between Short and Long Terms
Savers expecting rates to fall may prefer a longer-term CD. Locking in a fixed yield can protect income after rates on new CDs and savings accounts decline.
That protection comes with a trade-off. If rates rise instead, the depositor may be stuck earning less than the market rate. Leaving early can trigger a penalty, often measured as a portion of the interest earned.
Short-term CDs provide more frequent access to the market. They allow customers to reinvest sooner, but they offer less protection from falling rates.
- Longer terms can preserve a current yield if rates decline.
- Shorter terms offer flexibility if rates rise or cash needs change.
- Early-withdrawal penalties can reduce earnings and, in some cases, principal.
CD Ladders Can Reduce Timing Risk
A CD ladder divides a deposit among several maturity dates. For example, a saver could place funds in one-year, two-year, and three-year CDs rather than selecting one term.
As each CD matures, the customer can spend the cash or reinvest it at the available rate. This approach limits dependence on a single forecast. It also creates scheduled access to part of the money.
A ladder does not remove rate risk. Falling yields will still affect money that must be reinvested. Yet the method can soften the effect because not every deposit resets at once.
What Savers Should Compare
The advertised annual percentage yield is only one part of a CD decision. Depositors should review the maturity date, minimum balance, renewal policy, penalty terms, and deposit insurance status.
Automatic renewal deserves close attention. A bank may roll a matured CD into a new term after a short grace period. The replacement rate may be lower than competing offers.
Liquidity also matters. Money needed for emergencies or near-term bills may fit better in an insured savings account. A higher CD yield may not justify losing ready access to essential cash.
Signals That Could Shape Future Returns
Inflation readings will remain a key guide for rate policy. Persistent price growth can keep rates higher for longer. Weaker inflation and slower economic activity can increase the chance of cuts.
Employment data and consumer spending also matter. Strong demand may delay reductions, while a sharp slowdown could lead policymakers to act sooner.
Rate forecasts can change quickly, so savers should avoid treating any prediction as certain. A practical strategy matches CD terms with planned expenses, maintains emergency savings, and compares offers across insured institutions.
For depositors, the key issue is not simply whether rates rise or fall. It is how much flexibility they need and how long they want to guarantee today’s return. Future policy decisions will shape CD yields, but careful term selection can reduce the cost of being wrong.